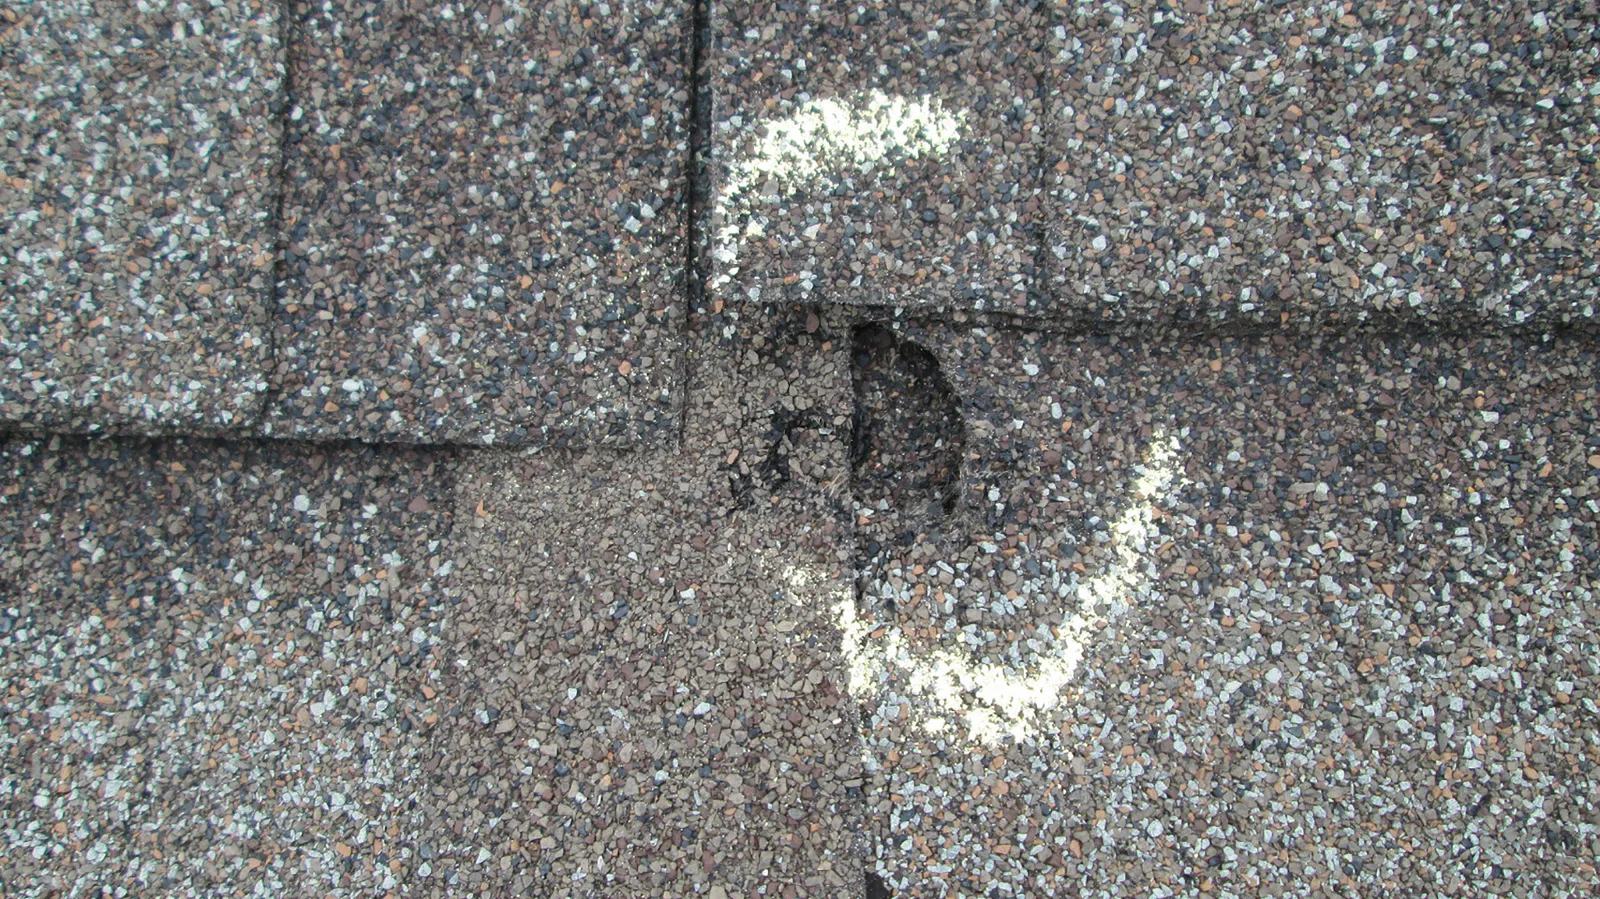
Roof insurance claims in Texas
Separate the roof repair decision from deductibles, depreciation and the insurer’s coverage decision.
Roof insurance claims and owner costs
A roof claim has two separate parts: the work needed to repair the damage and the policy’s payment for a covered loss. A free inspection helps with the roofing question. The insurer determines coverage.
Texas policies can pay on replacement-cost or actual-cash-value terms, and deductibles reduce the payment. Knowing those distinctions helps explain why the number on a claim statement can differ from a roofing proposal.
Why the first payment can be smaller than the repair
| Term | What it does | Practical effect |
|---|---|---|
| Deductible | Your share of a covered loss. A percentage deductible is based on the insured amount specified by the policy. | It is not simply a percentage of the roofing invoice. |
| Depreciation | An allowance for age and condition in the loss calculation. | It can reduce an initial payment or the final payment under actual-cash-value terms. |
| Replacement cost | Coverage based on replacement at current costs, subject to the policy. | Some withheld depreciation may be recoverable after required work and documentation. |
| Actual cash value | Replacement cost with depreciation deducted. | The owner can be responsible for more than the deductible. |
Keep the roof work and the claim moving in their proper order
| Step | How the roof and claim connect |
|---|---|
| Address immediate hazards | Keep clear of unsafe ceilings and electrical hazards. Roofing protection and repair needs do not wait for a payment decision. |
| Establish the roofing condition | An inspection helps define observed damage and the work needed. An event date provides context, not automatic proof of cause. |
| Apply the actual policy | The insurer handles coverage and claim payments. Roofing scope, existing damage and policy terms each have their own role. |
Wear, upgrades and exclusions still matter
Ordinary wear is not automatically storm damage. Choosing a more expensive material does not automatically make the upgrade part of a covered loss. Exclusions and any cosmetic-damage limitations depend on the policy.
Keep the claim and roof assessment distinct
A roofer’s repair assessment does not authorize a deductible waiver or guarantee approval. The Texas Department of Insurance provides official guidance about roof coverage and filing a claim.
Roof Insurance Claim FAQs
Should a nearby storm report decide whether I file?
A report records weather at a place and time. It does not establish damage to your roof or whether the policy covers it. The roof condition and the policy are the relevant starting points.
Can roofing work and the insurance estimate have different totals?
Yes. The scope, quantities, allowed prices, upgrades and policy limitations can differ. A difference needs explanation in the actual project and claim, not a blanket promise of payment.
Let’s take a look at your roof
If the roofing condition is still uncertain, start with a free inspection.